What Factors Affect Loan Approval With a Low Credit Score?
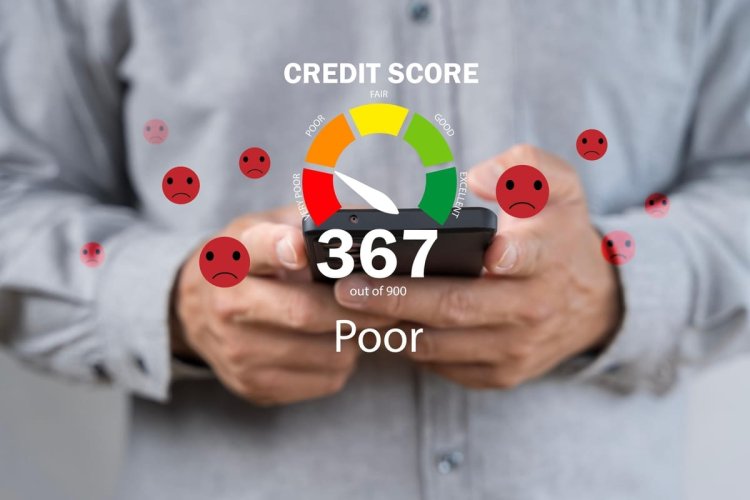
A low credit score generally falls below 580 on the FICO scale. Individuals with low scores are often perceived as high-risk borrowers, making it difficult to obtain loans or credit.
 jiya ahuja
Share this Post to earn Money ( Upto ₹100 per 1000 Views )
Getting a loan can be challenging, especially if you have a low credit score. A low credit score can significantly affect your chances of loan approval, making it crucial to understand the factors that lenders consider when assessing your application. This article will delve into the key elements that influence loan approval for individuals with low credit scores, focusing on personal loans, particularly for amounts like a personal loan of 50,000.
Understanding Credit Scores
What is a Credit Score?
A credit score is a numerical representation of a borrower’s credit history and financial behavior. Typically ranging from 300 to 850, a higher score indicates better creditworthiness. Lenders evaluate credit scores to gauge the likelihood of a borrower repaying their loan.
Low Credit Score Defined
A low credit score generally falls below 580 on the FICO scale. Individuals with low scores are often perceived as high-risk borrowers, making it difficult to obtain loans or credit. Factors contributing to a low score include missed payments, high credit utilization, and collections or bankruptcies.
Factors Affecting Loan Approval with a Low Credit Score
1. Debt-to-Income Ratio (DTI)
One of the most critical factors lenders use to assess your ability to repay a loan is your debt-to-income ratio. The DTI ratio measures your total monthly debt payments against your gross monthly income. A lower DTI indicates that you have more disposable income to allocate towards loan repayments.
How Lenders View DTI
Even with a low credit score, a favorable DTI can enhance your chances of loan approval. Lenders typically look for a DTI ratio below 36%. If you’re seeking a personal loan of 50000, showcasing a solid income and manageable debt can improve your application, even with credit challenges.
2. Employment History
Lenders want to ensure borrowers have a stable source of income, which is why employment history plays a significant role in loan approval. A consistent job history indicates financial stability, reliability, and the ability to meet repayment obligations.
Impact of Employment on Approval
If you’ve had a long-standing position, it may counterbalance a low credit score. Lenders are more inclined to approve loans for individuals demonstrating job stability, especially for larger loans like personal loans of 50,000.
3. Loan Amount and Type
The type and amount of loan requested can significantly impact your approval chances. Personal loans can vary greatly in size and purpose. For instance, requesting a larger amount, such as a personal loan of 50,000, can pose higher risk for lenders, especially for borrowers with low credit scores.
Assessing Loan Amount Requests
If your credit score is low, consider requesting a smaller amount or demonstrating a clear plan for how you’ll use the funds. Having a reasonable purpose can strengthen your case, showcasing responsibility in your borrowing habits.
4. Co-Signer Potential
Having a co-signer can be a game-changer for those with low credit scores. A co-signer is someone who agrees to take on the legal responsibility of repaying the loan if the primary borrower fails to do so.
Benefits of Co-Signing
Having a co-signer with a good credit score can enhance your chances of approval and may even result in better interest rates and terms. A personal loan of 50,000 can become more accessible with a co-signer, as the lender perceives reduced risk due to the co-signer’s creditworthiness.
5. Collateral
Secured loans require borrowers to provide collateral, which the lender can claim if the borrower defaults. This collateral reduces the lender's risk, making it easier for individuals with low credit scores to obtain loans.
Secured Versus Unsecured Loans
If you have valuable assets like a car or savings account, securing a personal loan using collateral can improve your approval odds. However, be cautious, as failing to repay a secured loan can result in the loss of your assets.
6. Credit History
While a low credit score is a red flag, lenders will also consider your entire credit history when evaluating your loan application. This history includes your payment activity, types of credit accounts, and the length of credit history.
Historical Context Matters
If you have a track record of timely payments on existing accounts, this can work in your favor. Lenders may view a few late payments as unfortunate but consider an overall positive payment history as a sign of potential future reliability.
7. Lender Policies and Market Conditions
Different lenders have varying risk appetites and policies regarding a low credit score loan. Additionally, economic conditions affecting the credit market can influence lending practices.
Researching Lender Options
Some institutions specialize in offering loans to individuals with poor credit. Researching multiple lenders can help you identify those who are more likely to approve your application, even with a loan amount like 50,000.
Conclusion
Obtaining a loan with a low credit score can be daunting, but it’s not impossible. Understanding the factors influencing loan approval—such as your DTI ratio, employment history, loan type, co-signer prospects, collateral, credit history, and lender policies—can help you navigate the lending landscape more effectively. Although your low credit score presents challenges, focusing on these critical elements can enhance your chances of approval for a personal loan of 50,000 or potentially more. Being proactive in improving your creditworthiness and seeking suitable loan options will ultimately assist you in achieving your financial goals.